Key takeaways
- Permanent establishment (PE) creates a taxable presence: Your company can trigger PE through a fixed place of business, dependent-agent activity, certain long-term projects, or other qualifying business activities.
- PE rules vary by country: Domestic law and applicable tax treaties determine thresholds, exemptions, and tax obligations that apply.
- Remote work can affect PE exposure: Tax authorities can look at how often team members work from a location, what activities they perform, and whether there's a commercial reason for their presence in the country.
- Managing PE risk warrants ongoing review: Monitor local activities, contracting authority, remote-work arrangements, and changes in your operations as you expand across borders.
One of the most important things to consider before you enter a new market is permanent establishment (PE). PE can subject your company to corporate taxes and a host of new obligations. Rules vary widely depending on local law, applicable tax treaties, how your team works, and the type of business activities involved.
As your company expands internationally, understanding potential PE triggers can help you spot tax and compliance issues early and avoid surprises that could derail your plans. Here's what you need to know about permanent establishment, how it works, and what steps you can take to manage risks.
What is a permanent establishment?
Permanent establishment is a tax concept countries use to determine whether your business has enough of a presence to levy taxes on certain profits from local activities. Establishing a taxable presence in a country can trigger corporate income tax and other compliance obligations.
PE can arise in several ways. Some involve deliberate business activities, such as maintaining a fixed place of business, operating through a dependent agent, or carrying out certain projects long enough to meet an applicable threshold. At other times, your company can inadvertently create PE through cross-border operations or team members’ activities. Exact rules vary by country and applicable tax treaty.
How tax treaties impact permanent establishment
Tax treaties help determine which country can tax particular business income and can reduce the risk of double taxation. Many treaties base their PE rules on the Organisation for Economic Co-operation and Development (OECD) Model Tax Convention or the United Nations (UN) Model Double Taxation Convention.
These models provide a framework. However, individual treaties set the ultimate rules. A treaty can have different thresholds for construction projects, services, dependent agents, or other activities. If no applicable treaty exists, the host country's domestic tax rules typically determine whether your company's activities create a taxable presence.
How does a permanent establishment work?
Once companies create a permanent establishment, local governments can impose taxes on the profits attributable to that PE. Your company may also have filing and reporting obligations under local tax law. Failing to meet those requirements could result in compliance issues and penalties.
When entering a new market, you need to review applicable laws and potential PE triggers.
A fixed place of business is one common way PE can arise. If you have an office, factory, workshop, or another location you use for regular business activities, you may create a PE.
Tax authorities will look at whether:
- You have a specific office or business location within the country.
- Team members regularly carry out business activities there.
- Your company uses the location on an ongoing basis.
Your company can also create PE when working with a dependent agent. Unlike agents that operate independently and typically represent multiple clients, a dependent agent acts on your company's behalf. In the U.K., for example, PE can arise when a person habitually concludes contracts or is the primary driver of contract closure.
Some treaties also use time-based thresholds. For instance, the U.S.-Thailand tax treaty determines PE when certain consultancy services extend beyond 90 days within a 12-month period. The same treaty applies a more-than-120-day threshold for some construction or installation projects.
Permanent establishment exemptions
Certain activities can fall outside PE rules when they’re limited in scope and considered preparatory or auxiliary to your core business. Common examples include:
- Storing, displaying, or delivering goods.
- Maintaining inventory for storage or processing.
- Purchasing goods or collecting information.
- Using a fixed place of business for limited support activities.
These exceptions aren't universal. The exact treatment depends on local law and the applicable tax treaty. Some treaties also have anti-fragmentation rules that prevent companies from splitting related business activities across locations or entities to claim PE exemptions.
For example, some bilateral treaties specifically exclude some storage or delivery activities from PE rules when companies meet other treaty conditions.
How to determine a permanent establishment
Determining whether your company has a PE starts with examining what your business does in the country.
Consider these key questions:
- Physical presence: Does your company use an office, workshop, or other locations for ongoing business operations? Do you have team members working remotely from a home office?
- Duration: How long do your team members, contractors, or projects operate in the country?
- Contract authority: Does anyone locally have authority to conclude contracts or play a principal role in securing them on your company's behalf?
- Business activities: Are local team members carrying out core revenue-generating work, or are their activities limited to preparatory or auxiliary functions?
- Treaty rules: Does an applicable tax treaty change the domestic PE standard or set specific time thresholds?
No single factor determines PE in every case. Understanding whether your company has a taxable presence in another country means looking at your operations as a whole. Tax authorities will look at the overall facts and circumstances. As a result, when your company begins to expand across borders, you need to review both local law and applicable treaties before assuming your operations fall outside PE rules.
Working with an employer of record (EOR) can simplify global hiring while your company evaluates permanent establishment risks. G-P EOR gives you everything you need to hire compliantly in 180+ countries — without setting up entities. We have the largest team of in-region HR and legal experts in the industry to help you navigate PE, so you can build and manage your global team, quickly and compliantly.
Branch vs. permanent establishment
A branch and a permanent establishment can both create a taxable presence in another country. However, they aren't the same, and they affect your tax obligations, and compliance in different ways.
A registered branch office is a formal extension of the parent company. Usually, companies create them through deliberate local registration. Branch offices don't have a separate legal identity from the parent, acting instead as an extension of your existing organization.
An unregistered permanent establishment, by contrast, can arise through your company's activities. Also known as a "de facto permanent establishment," you can inadvertently create one even if you never register a branch or local entity. Tax authorities assess how your business operates locally to determine whether its activities create a sufficient taxable presence to trigger tax obligations.
A wholly owned subsidiary is different from both. It's a separate legal entity owned by the parent company. While registered branches are an extension, subsidiaries are separate. This structure can shield the parent company from certain liabilities, subject to local law and the circumstances involved.
Operational dimension | Registered branch office | Unregistered permanent establishment (de facto) | Wholly owned subsidiary |
|---|---|---|---|
Legal personality | Extension of the parent company | No separate legal entity | Separate legal entity |
Corporate liability | Parent generally remains liable | Parent remains responsible for local activities | Liability generally sits with the subsidiary |
Registration process | Formal local registration | Can arise without registration | Formal incorporation required |
Corporate income tax | Local profits generally subject to tax | Profits attributable to the PE typically subject to tax | Subsidiary usually taxed as a local company |
Profit repatriation | Profits typically flow directly to the parent, subject to local tax rules | No separate repatriation; attributed profits remain part of the parent company | Distributions to the parent may involve dividends and related tax rules |
Types of permanent establishment and examples
Permanent establishment can take different forms, depending on how your company operates in a country. Understanding the three types can help you identify where tax exposure can arise.
1. Physical permanent establishment
A physical permanent establishment is when your company maintains a fixed place of business in another country. Common examples include:
- Offices
- Workshops
- Factories
- Construction or installation sites
- Locations used to extract natural resources
Remote work can make the situation more complicated. An employee's home office doesn't automatically create PE. However, tax authorities will look at how often team members work from the location, whether your company effectively uses it as a place of business, and whether there's a commercial reason for a professional to work from that country.
Modern OECD guidance takes the broader commercial context into account. A home office becomes more relevant to PE analysis when the location effectively supports your company's business in that market. For example, a professional may manage local customers, develop business, or carry out other market-specific activities there. The distinction is essentially where someone works versus where your company conducts business.
Two factors are particularly important:
- 50% benchmark: Working from home or another non-company location for at least half of a professional's total working time over a 12-month period can make a location more relevant in PE assessments.
- Commercial reason: Meeting the 50% benchmark alone doesn't trigger PE. Tax authorities also consider whether there's a legitimate commercial reason for a professional to work from that country rather than primarily for personal convenience or talent retention.
2. Digital permanent establishment
In some countries, digital or economic nexus rules apply, and businesses may owe taxes if there’s substantial activity in the market even without a traditional physical presence. Those rules can apply if your company generates significant revenue, provides digital services, or maintains a large user base in the country.
India, for example, uses the significant economic presence (SEP) standard. Under current rules, it can apply when certain transactions with people in India exceed INR 20 million during the tax year. The SEP standard can also apply when a business systematically engages with at least 300,000 users in India.
Having an SEP isn't the same as having a traditional permanent establishment. India treats it as a domestic-law business connection concept, which means that companies also need to consider whether an applicable tax treaty changes the result.
3. Agent-based permanent establishment
Your company can have a PE through the activities of a dependent agent in another country. This typically happens when a person or business acts on your behalf and has significant involvement in generating or finalizing contracts.
Agents don't always need formal signing authority to create PE. Under modern treaty standards, permanent establishment risks can also increase when someone regularly plays the principal role leading to contracts your company routinely concludes. For example, a local sales representative might negotiate the key terms of a deal with a customer, leaving your company to formally sign the agreement with little or no further negotiation.
Independent agents generally present lower PE exposure when acting on their own behalf and conducting business in the ordinary course of their operations.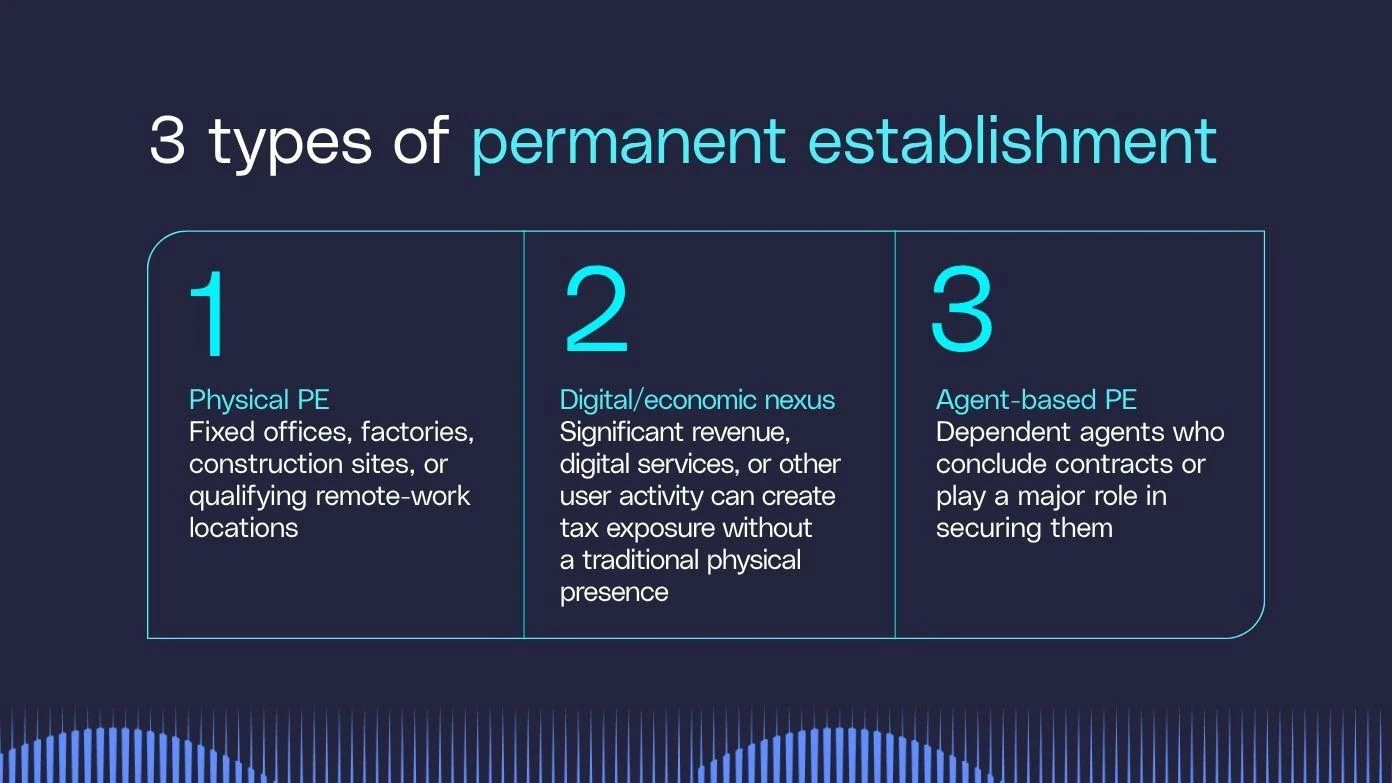
How permanent establishment rules vary among countries
Permanent establishment rules vary across jurisdictions, particularly when remote work is part of the equation. Domestic law and applicable tax treaties shape how each country evaluates whether your activities create a taxable presence, with domestic law as the final authority if no applicable treaty exists.
Germany, for example, generally doesn't treat an employee's home office as a PE when a company lacks sufficient control over the space. This can remain true even if your company covers home office costs or doesn't provide another workplace. However, management activities can receive different treatment, especially when senior executives make key business decisions from the country.
Austria takes a more fact-specific approach. Authorities will consider how frequently an employee works from home, whether your company provides another workspace, and whether there's a commercial reason for the arrangement. Remote work that accounts for 50% or more of a professional's working time becomes a relevant factor, but it doesn't determine the outcome on its own.
How permanent establishment rules vary by industry
PE rules can also differ based on the type of work your company performs. Some industries rely heavily on physical projects, while others focus more on services, contracts, or local representatives.
- Construction: Construction and installation projects can create a PE when they continue beyond treaty-specific time limits. Under the OECD Model, the threshold is generally more than 12 months, while the UN Model uses a shorter six-month limit.
- Consulting and services: Service-based companies may face different tests because they often operate without a fixed office. Some treaties use time-based service PE rules, including an 183-day threshold within a 12-month period.
- Brokerage and sales: Agent relationships matter more in industries where local representatives negotiate or secure business. PE exposure can increase when an agent depends heavily on your company or regularly plays a key role in concluding contracts.
The exact standard still depends on local law and an applicable treaty, but industry-specific activity can shape which PE tests matter most.
Risks and benefits of having a permanent establishment
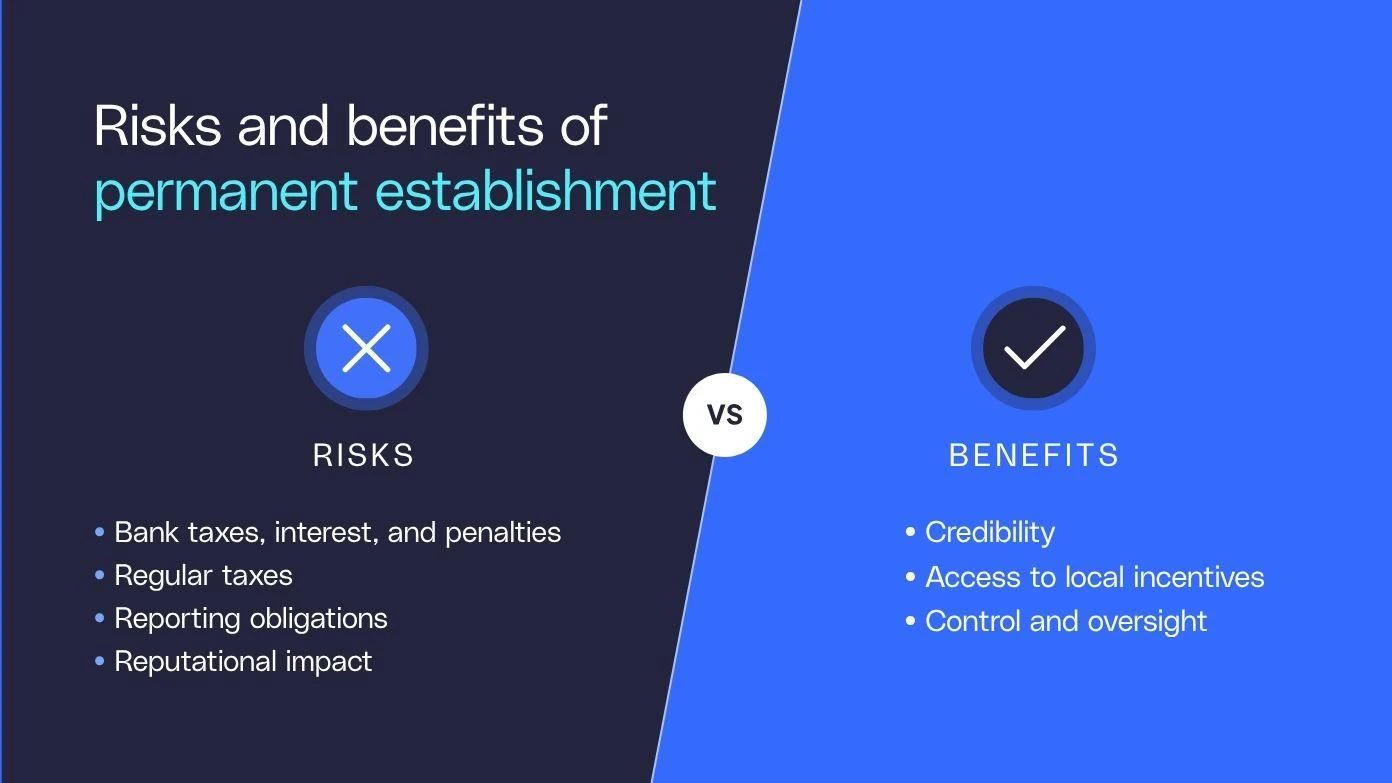
Having a permanent establishment can create both compliance burdens and strategic advantages, often depending on whether that presence is intentional.
Risks
The biggest risk is creating a PE before your company has the systems in place to manage local tax and reporting obligations. Potential consequences of permanent establishment include:
- Back taxes, interest, and penalties: Your company can owe tax for prior periods if authorities determine that PE already existed.
- Additional compliance requirements: PE can bring corporate tax filing, recordkeeping, and other local reporting obligations.
- Higher administrative costs: New obligations can increase costs for local tax, accounting, legal, or HR support.
- Reputational concerns: Unexpected tax or compliance issues can complicate relationships with local authorities, team members, and business partners.
Benefits
The benefits of having a permanent establishment are most relevant when your company intentionally establishes a formal, legal presence. A registered branch or other planned local structure can support broader business goals and offer several advantages.
- Local credibility: A formal presence can strengthen credibility with customers, business partners, and authorities.
- Access to incentives: Some jurisdictions offer tax incentives, grants, and other programs to qualifying local operations.
- Greater market access: A local presence can make it easier to hire, open bank accounts, or secure contracts.
- More operational control: Managing local activities directly can give your company greater oversight of day-to-day operations.
What matters most here is intent. An intentional local presence can support expansion plans, while an unexpected PE can create tax and compliance obligations your company didn't anticipate.
How to manage permanent establishment risk
You can't always eliminate permanent establishment exposure, but you can reduce unexpected risk by understanding how your people and operations work across borders. If your company has already created a PE, reducing future exposure means changing the activities or conditions that caused it. Your company may need to resolve existing tax and filing obligations separately.
- Know the local rules: Review domestic tax law and any applicable treaty before entering a new market. Pay close attention to fixed-place, agent, service, and project-duration tests.
- Draft clear local agreements: Make sure employment, contractor, and agency agreements reflect local requirements and accurately define every person's role, authority, and work arrangement.
How to mitigate permanent establishment exposure
You can also take practical steps to reduce the chance that day-to-day operations create an unexpected taxable presence.
- Set clear contracting authority: Define who can negotiate, finalize, and approve contracts. Local team members who regularly play a major role in securing deals can increase permanent establishment risk.
- Track remote work arrangements: Document where team members work, how often they work there, and whether the arrangement serves a business purpose or primarily reflects personal preference.
- Review local activities: Consider whether work in the country supports core revenue-generating operations or remains limited to preparatory or auxiliary functions.
- Reassess as operations grow: Your permanent establishment risk can change as headcount, responsibilities, customer activity, or time spent in the country changes.
- Consider an EOR for hiring: If you want to test a new market before committing to your own entity, an EOR can provide a flexible hiring option while you evaluate your company’s long-term operating structure.
Reduce PE risk with G-P EOR
Understanding local laws, documenting work arrangements, and reviewing how your business operates can help you identify exposure before it creates unexpected tax obligations.
G-P EOR gives you a faster path to building global teams, without committing to entity establishment from day one. We’ve embedded 14+ years of legal and HR expertise into our Global Employment Platform, allowing you to hire and scale compliantly in 180+ countries in minutes.
Reduce compliance risk with expertise-backed guidance in every workflow.
Book a demo today to see how G-P can support your company's global expansion.
FAQs
How do I avoid triggering permanent establishment?
You can reduce permanent establishment risk by reviewing local tax rules and applicable treaties before entering a new market. Pay attention to fixed business locations, contract authority, project duration, remote work arrangements, and the activities local team members perform. Your company should reassess PE exposure as operations change.
How does having a permanent establishment affect my tax obligations?
Once your company creates a permanent establishment, the host country can generally tax profits attributable to that PE. Your company may also need to meet local corporate tax filing, reporting, and recordkeeping requirements. Exact obligations depend on domestic law and any applicable tax treaty.
Can a remote worker trigger permanent establishment?
A remote worker's home office can contribute to PE exposure, but it depends on the facts and circumstances. Tax authorities consider how often a team member works from the location, whether your company effectively uses it as a place of business, and whether there's a commercial reason for them to work from that country. Under current OECD guidance, the 50% benchmark is an important factor, but it doesn't create PE on its own.
What's the difference between a dependent agent and an independent agent for PE purposes?
A dependent agent acts on your company's behalf and can trigger PE when they regularly conclude contracts or play a major role in securing contracts your company later approves. Independent agents generally pose a lower PE risk when acting on their own behalf and conducting business in the ordinary course of their operations.
What is a tax treaty?
A tax treaty is an agreement between two or more countries that helps determine which country can tax particular income and reduces the risk of double taxation. Many treaties also define permanent establishment and set thresholds for activities such as construction projects, services, or dependent-agent activities.