


Key takeaways:
- Defining the "startup valley of death": This is the period after a startup begins operating but before it brings in any revenue.
- Causes of the startup valley of death: The valley of death is often worsened by scaling too fast, committing to excessive expenses, and failing to collect payment promptly.
- Escaping issues with funding: Secure funding from venture capitalists, angel investors, and online platforms to maintain a solid budget.
- Avoiding the valley of death with global hiring: Hiring across borders gives you access to a diverse talent pool and expands market opportunities for long-term success. For the most convenient hiring experience, partner with an employer of record (EOR) like G-P.
Many businesses meet their downfall during the so-called “startup valley of death.” What is this critical phase, and how can entrepreneurs survive the death valley curve? We'll go over the details of this common issue and help you find ways to avoid it. By learning about initial hurdles today, you can build a better startup tomorrow.
What is the startup death valley curve?
The death valley curve, also known as the valley of death, is the period when a startup has begun operating but has yet to bring in revenue from customers. The longer a company remains in the startup curve, the more likely it is to fail due to a higher burn rate. Unfortunately, the faster a new company consumes cash reserves without generating profit, the less chance it has of success.
A company’s trajectory through the startup valley of death will depend on both its industry and business plans. Typically, a young startup struggling to break into the market experiences a sudden nosedive. Once the business gains momentum and hones in on its market fit, the growth journey transforms into a gradual ascent. This is most commonly seen in the notorious J-curve trendline of software companies which tend to have an immediate, dramatic gain following an initial loss.
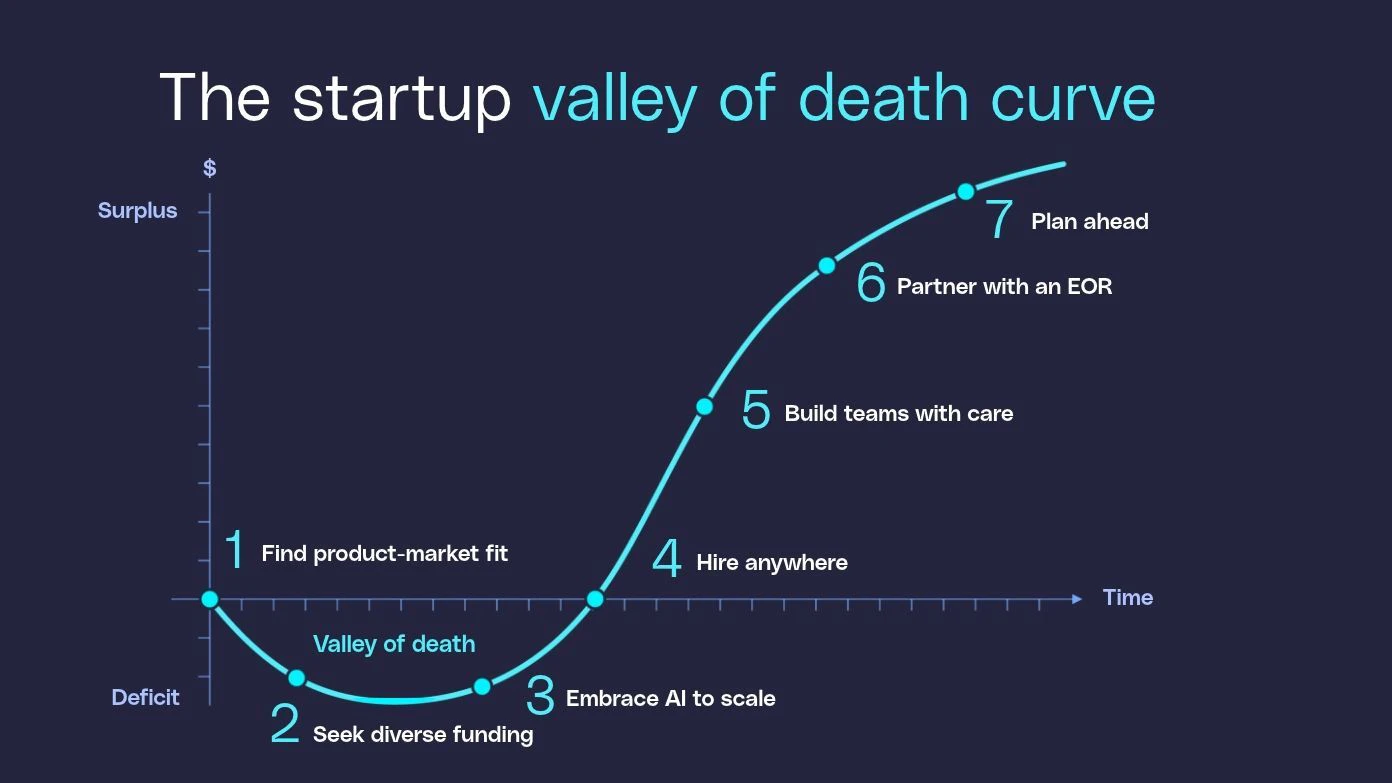
However, the exact trajectory you'll experience can vary based on your industry. Climate-tech startups, for example, confront the valley of death four times: during setup, networking, scaling, and further technological advancements. While this type of variety might sound intimidating, there's no need to stress. No matter what industry you work in, there are some key steps you can master to help your company make it through.
Primary causes of startup failure in the death valley curve
Did you know that over 20% of new businesses fail in their first year, and nearly 50% fail by their fifth year? If you want to avoid the valley of death, it's essential to understand the causes. Here are the key reasons that a company ends up in the valley of death:
- Cash depletion: Of course, one of the most common warning signs is cash depletion. Running out of cash is a big problem not only because it makes it hard to manage expenses but also because it indicates deep-seated operational issues. Research shows that companies start to experience cash depletion when they do things like agree to poor payment terms or decide to work with the wrong supplier.
- Premature scaling: Many businesses have a promising start but then make the mistake of getting too big too fast. Spending all your capital on giant offices, bulk supplies, and other things you won't use for a while makes it hard to escape the valley of death.
- Lack of market need: No startup can succeed if it can't find customers. Failing to do adequate research can lead to a business putting all its funds into services and products no one will purchase.
- Costly structural commitments: Sinking all your funds into big structural updates, like creating a local entity or signing up for a rigid lease, is another issue frequently linked to the death valley curve. Not only does this result in bigger expenses for you, but it also shows that your company is failing to properly research smart business practices.
- Lagging payments: Many new startups make the mistake of having payment structures that don't line up with their expense structures. For example, some companies will collect payments every 60 days but have payroll that runs on a weekly basis. If anything goes wrong, this can create a death valley curve that's hard to escape.
A comparison of other common startup issues:
|
Failure vector |
Statistical impact |
Operational root cause |
Strategic mitigation |
|---|---|---|---|
|
Lack of customers |
42% |
Building features without taking into account user needs |
Better market research strategies |
|
Premature capital depletion |
35% |
Excessively high fixed overhead expenses and very fast cash flow |
More flexibility for staffing and other expenses plus better cash forecasting |
|
Friction between team members |
23% |
Unclear roles for team members, unequal payroll structures, and major skill gaps |
Clearer communication and helpful incentives like stock |
|
Unnecessary bureaucracy |
37% |
Registering for foreign entities and setting up taxable entities too soon |
Working with helpful third-party providers like an employer of record |
How to overcome the startup valley of death in 7 simple steps
Every startup will struggle with things like narrowing its target audience or securing funding. However, even though these issues are linked to the startup valley of death, they don't guarantee disaster. Avoiding the valley of death is all about making the right choices when you inevitably face adversity. With the right guardrails in place, you can invest in your company’s development while maintaining a solid budget. Follow these seven startup success tips to improve your company’s chances from day one.
1. Determine product-market fit with a minimum viable product (MVP)
What’s the first step in researching and developing your business? Determine if your product or service is something people want or need. You'll need to conduct market research to demonstrate your product’s fit within a particular market.
One particularly popular approach is creating a minimum viable product. A minimum viable product is not a technology prototype. Instead, it's a way to test a business idea's value to your target audience and venture capital leaders. Start by introducing a version of your product that allows your team to source the maximum amount of proven customer knowledge with minimum effort.
2. Seek diverse startup funding
Cash flow is a major challenge for startups. In fact, 58% of startups have less than USD 25,000 at their disposal during the startup phase. A strong investment foundation involves a clear business model that maintains a solid budget. Seeking funding from multiple sources is one of the key success factors for startups.
You may want to partner with venture capitalists, work with angel investors, or seek government and organization-based grant funding. You should also consider online investment platforms such as crowdfunding. Looking for a more secure solution? Consider partnering with an incubator firm for added support.
3. Embrace AI to scale quickly
I appreciate how G-P Assist helps me streamline and standardize my requests. I especially enjoy the speed of their AI tool and G-P's flexibility to adapt to my specific needs when necessary.
Technology is one of the key factors for business success, and artificial intelligence (AI) technology is already having a profound impact on how companies break into new markets and scale globally. With the right solutions in place, you can streamline hiring, onboarding, payroll, and other business needs.
From improving workforce management to promoting communication, AI can help you increase collaboration, streamline marketing workflows with AI-generated content, and even improve customer acquisition by automating online communication via widgets.
4. Hire anywhere to drive growth everywhere
Growing into new markets ultimately increases your revenue and your chance of long-term success. Global growth expands your market opportunities, attracts customers before competitors, and unlocks diverse talent pools to help you find the most qualified people for every job.
Not sure where to start? At G-P, we have over a decade of experience helping companies learn how to launch a successful startup on a global basis. From early-stage startups to large-scale enterprises, our fully customizable suite of global employment products is designed to accelerate your growth, no matter which step is next.
5. Build your teams with care
Building a strong team is one of the keys to a successful startup because 23% of startups fail due to poor team organization. Hiring while your company is still on the death valley curve takes some extra thought. Start with the executive team and work downward as resources permit. Generally, startups should look for candidates who are flexible enough to assume multiple responsibilities, solve problems under pressure, and embrace the company’s mission.
While a startup’s founders often assume the roles of chief executive officer and chief information officer, they must find talented individuals to fill other roles, including:
- Product managers
- Sales managers
- Business development managers
- Chief technology officers
- Chief marketing officers
- Customer service representatives
Remember: Your needs will change as your business grows, and you need to land those first critical hires to build a team that can set you up for success. Unlike in years past, you don’t need to start a business where the talent is. With the support of growth experts like G-P, startups can think globally about their team from the start, from anywhere in the world.
6. Partner with an employer of record
Partnering with an employer of record (EOR) can encourage startup growth, especially when expanding into international markets. But what is an EOR, and what are the benefits of partnering with an EOR? An EOR serves as the legal employer, handling the employment-related HR and legal complexities so that you can focus on your team’s day-to-day responsibilities and growing your business.
While founders are most concerned about implementing their ideas and achieving product-market fit, they often have little bandwidth to deal with onboarding, payroll, contracts, local labor laws, and tax compliance. With an EOR like G-P EOR, you can begin hiring globally starting in just minutes, regardless of your entity status.
7. Take strides to plan ahead
The final secret to startup success? Be ready for anything financially and operationally.
Alongside an experienced team, it’s essential to ensure your business has raised enough funds to cushion potential fallbacks during the death valley curve. Yet, 33% of employer startup firms have a capital level of USD 10,000 or lower. Tight budgets across verticals leave companies with very little margin of error, and this limits their chance of success. With that in mind, it’s critical to start a business the right way, with the right amount of funding.
Regardless of your industry, it’s best to raise more money than budgeted. Markets are constantly evolving, and the future can be unpredictable.
Stay ahead of the curve with G-P
As the recognized leader of the employer of record category, we continue to pave the way with new technology for new times. Our Global Employment Platform offers everything companies at any stage need to find, hire, and manage global teams – quickly and compliantly – in 180+ countries. Request a proposal today to learn more about how we can help you break through “death valley” tomorrow.
 FAQs
What is the startup valley of death?
The startup valley of death occurs when a business is operating but is not yet bringing in meaningful amounts of cash yet.
Why do most startups fail in the valley of death?
When companies stay in the valley of death for too long, it becomes unsustainable for them to keep operating their business.
How long does the startup valley of death last?
This varies depending on your business and industry. Some companies may be in the valley of death for just a few weeks, while others may reenter it every time they launch the next stage of their business.
What are the key factors for business success during early growth?
In order to succeed, businesses need a strong team, reliable cash flow, and a clear budget.
How can an employer of record help startups survive the valley of death?
An employer of record provides a flexible way to hire talented workers without overextending yourself financially.


